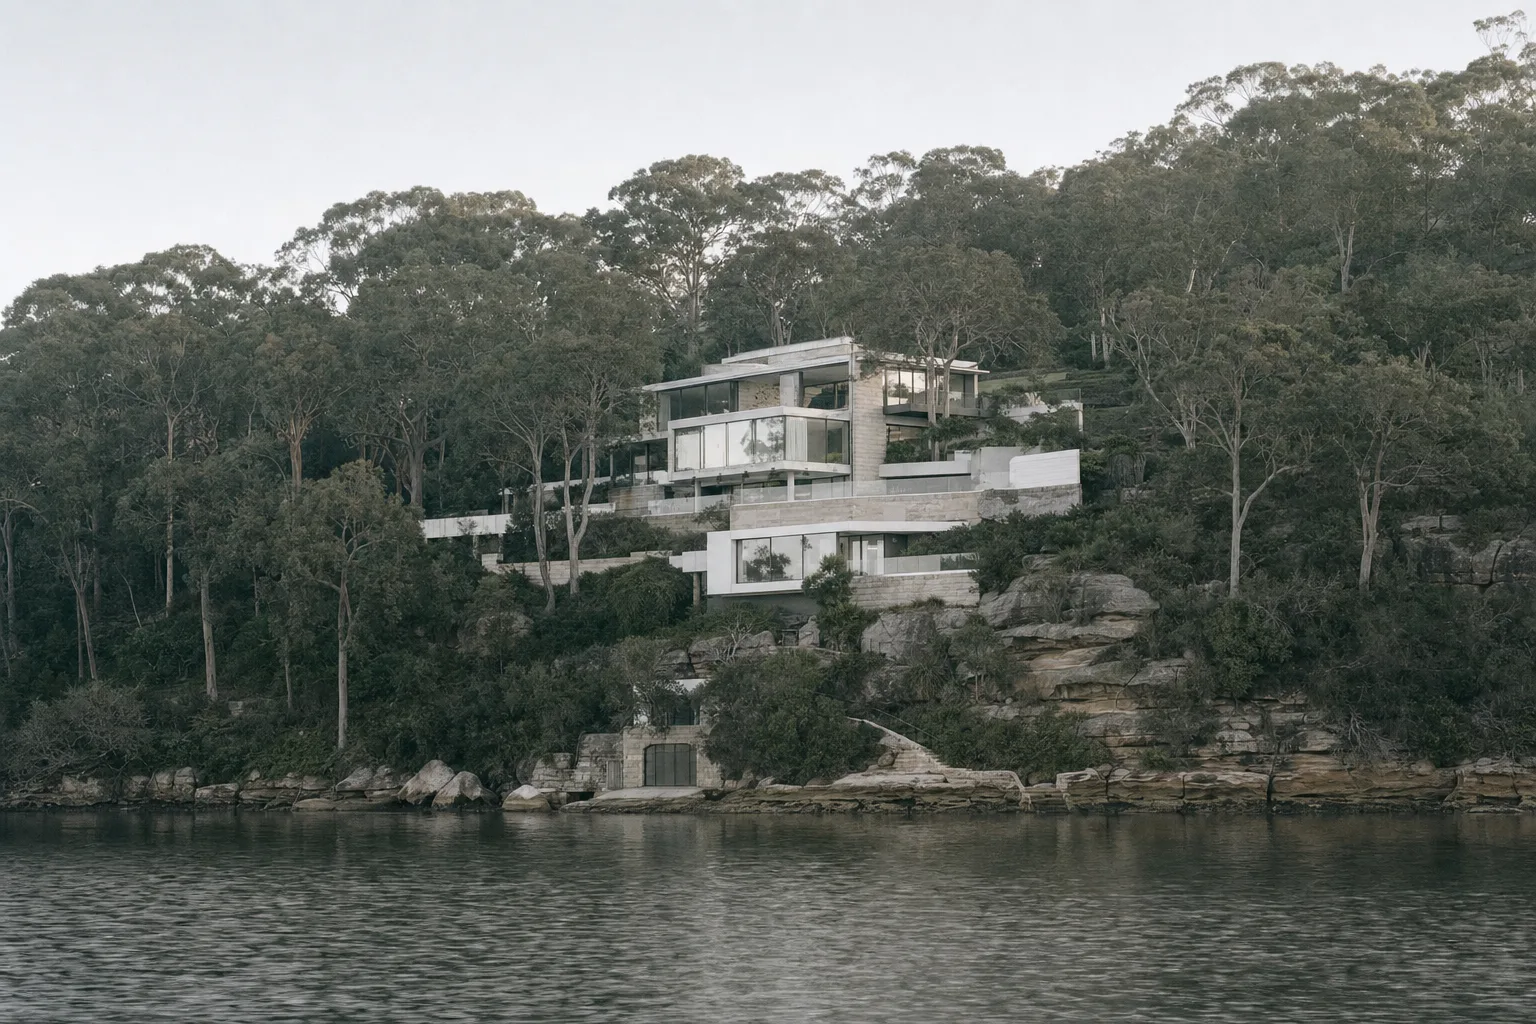
Homes a standard policy wasn’t built for.
Homes that would cost from about $1.5 million to rebuild. Architect-designed and custom-built homes, heritage homes, waterfront homes. Homes with a pool house, a cellar, an art collection or jewellery that travels.
Below that figure, a mainstream policy is usually better value, and we’ll tell you so.
The house, and everything in it.
- Building: rebuilt to the same standard, with the same materials. Better policies allow for the rebuild costing more than expected.
- Contents: new for old, with valuable pieces listed individually so they aren’t caught by per-item limits.
- Art and collections: covered at an agreed value, with new pieces covered automatically for a while.
- Jewellery and watches: covered anywhere in the world, for loss as well as theft.
- Wine: the whole cellar, including breakage and cooling failure on better policies.
- Personal liability: a higher limit to suit a larger property.
Each one raises its own questions.
Large homes need the rebuild cost right, and a policy with room if it runs over. More on mansion insurance.
Heritage homes need slate, sandstone and old joinery matched, not just replaced. The insurer needs to know about them upfront.
Waterfront homes are priced for flood, storm and salt. Some insurers won’t cover them, and we’ll tell you which ones will.
Architect-designed homes are rebuilt to their own plans, so keep a copy with your policy.
Who can cover your home.
Tell us about your home once. Public records fill in most of the details, so you just check them.
We then send it to every insurer on our panel that can take it: Castle & Sure up to $5 million, Blue Zebra (backed by Chubb, AIG and HDI) up to $7 million, Prevail Elite from $3 million, and a private clients desk above that.
You’ll see who can cover you before you give anyone your phone number. How it works.
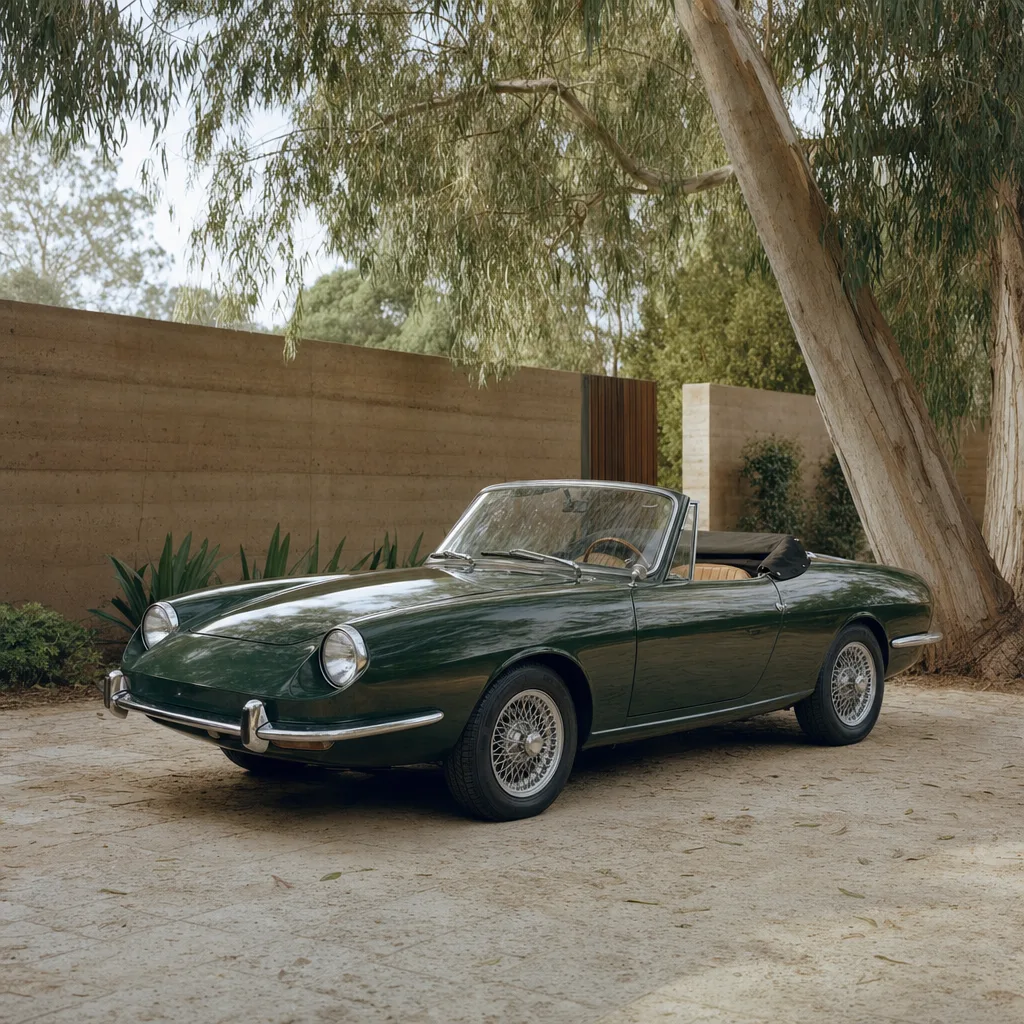
Prestige and classic cars, on the same application.
We place your cars with the specialist that insures them, and you have one person to call. More on luxury car insurance.
Luxury home insurance FAQs
What counts as a luxury or high-value home for insurance?
Usually a home that would cost more than about $1.5 million to rebuild, or one with things a standard policy caps or leaves out: heritage features, architect-designed finishes, a pool house, a cellar, valuable art or jewellery. Insurers call it luxury, prestige, high-value or high-net-worth home insurance. They mean much the same thing.
How is prestige home insurance different from a standard home policy?
Mostly in the limits. High-value policies typically cover the full rebuild cost with extra room if it runs over, pay agreed values for listed items, cover jewellery anywhere in the world, treat art and wine as their own sections, and carry a higher liability limit. A standard policy caps most of these.
Does a custom-built, heritage or waterfront home need special insurance?
Usually, yes. A custom home is rebuilt to its own plans. Heritage features have to be matched, and the insurer needs to know about them upfront. Waterfront homes are priced for flood and storm risk, and some insurers won’t cover them at all.
Which insurers write high-value homes in Australia?
On our panel: Castle and Sure up to a $5 million building sum, Blue Zebra (backed by Chubb, AIG and HDI) up to $7 million, Prevail Elite from $3 million, and a private clients desk above that. Which ones can cover your home depends mostly on the rebuild cost.
What is the best luxury home insurance in Australia?
There isn’t one best policy. A heritage home, a coastal home and a new build full of art are different risks, and an insurer that suits one may not cover another. We put your home to every insurer that can take it and show you the policies side by side.
How is the rebuild cost worked out?
We start with public records, which give a range based on the home’s size, construction and age. You then give your own figure and we check it against that range. For anything unusual, like heritage materials, a tricky site or a very large home, a quantity surveyor’s estimate is worth getting. More on rebuild cost.
Is the advice on this page personal advice?
No. Everything on this site is general information only and doesn’t take your objectives, financial situation or needs into account. Read the product disclosure statement before deciding, and ask us if anything is unclear.
Luxury Cover arranges insurance as a broker. The policies are issued by the insurers, and what they cover depends on the policy you choose. Each quote links to its product disclosure statement. General information only.