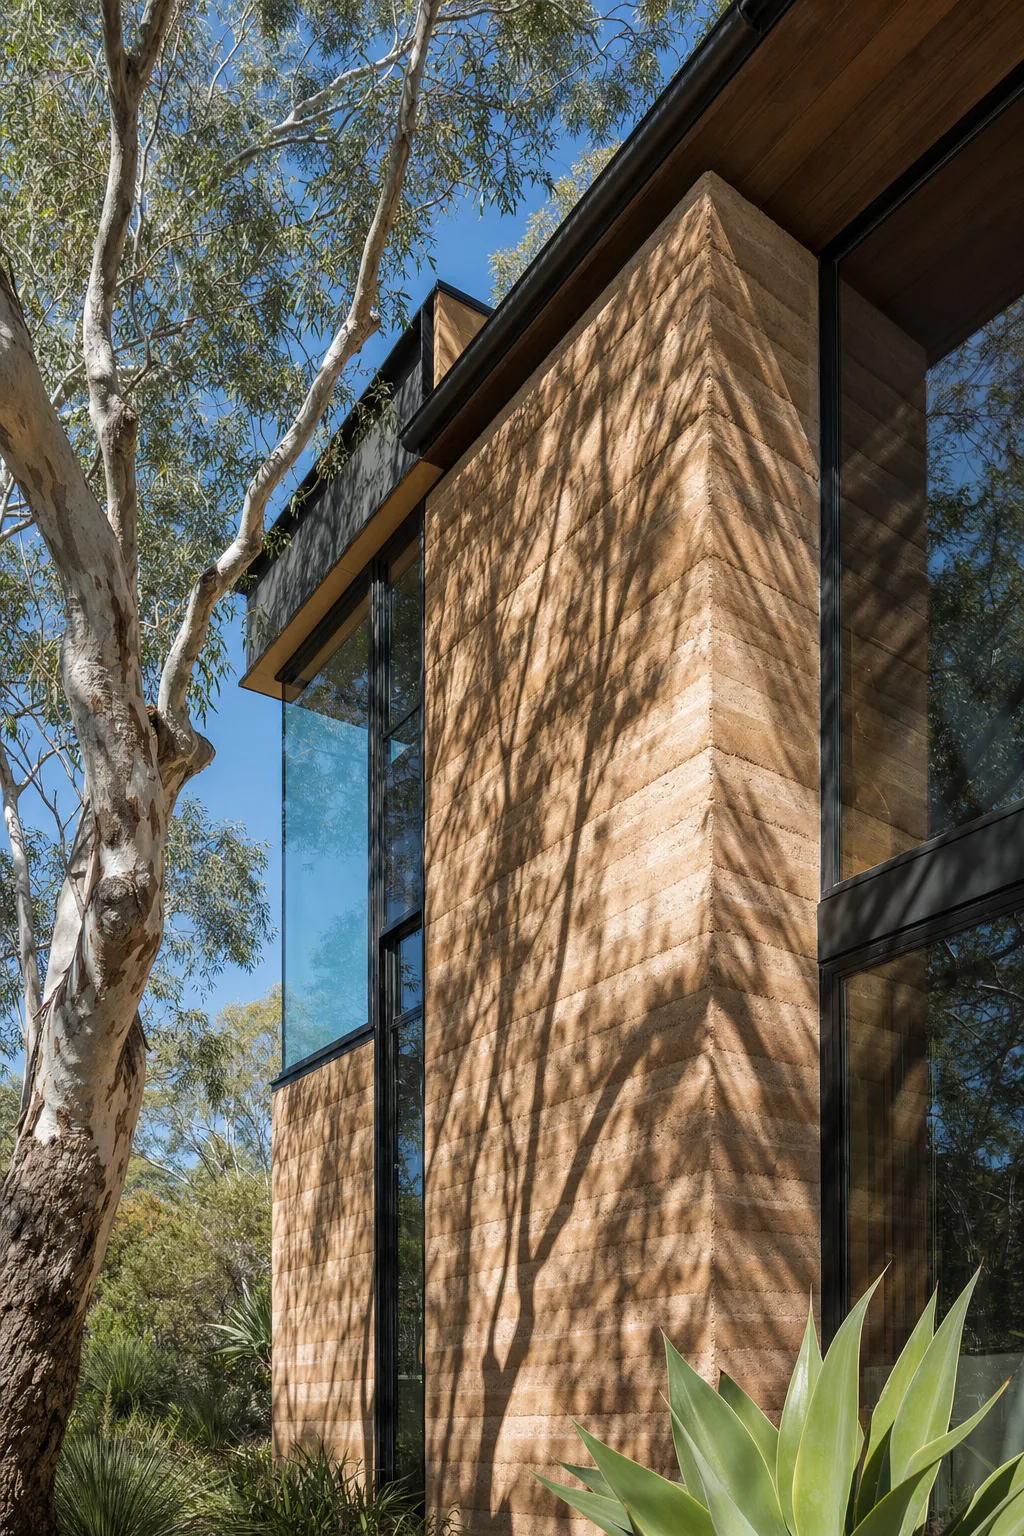
The house, rebuilt to the same standard.
Covers damage to the home from things like storm, fire, water and impact, and pays to repair or rebuild it. It’s based on the rebuild cost, not the market value. Better policies allow for the rebuild costing more than the sum insured.
You’ll be asked: when it was built and what from, the rebuild cost (we check yours against public records), any heritage listing, who lives there, and your security. Mention things like a slate roof or rendered walls, since they cost more to replace.
Everything inside, replaced new for old.
Covers furniture, appliances, clothes and electronics. Better policies replace them new for old, with no deduction for age. Valuable items are best listed individually, because unlisted items have per-item limits.
You’ll be asked: a total contents value, and a list of the pieces worth naming. That’s where the sections below come in.
Art, antiques and collections, at an agreed value.
Listed pieces are covered for an agreed value, so a claim pays the figure on your policy. Most policies also cover new purchases automatically for a while, and pieces in transit or on loan if you tell us.
You’ll be asked: a list of pieces with a recent valuation for anything significant, and how they’re stored. Mention pairs and sets. A good policy covers the loss in value to the whole set, not just the missing piece.
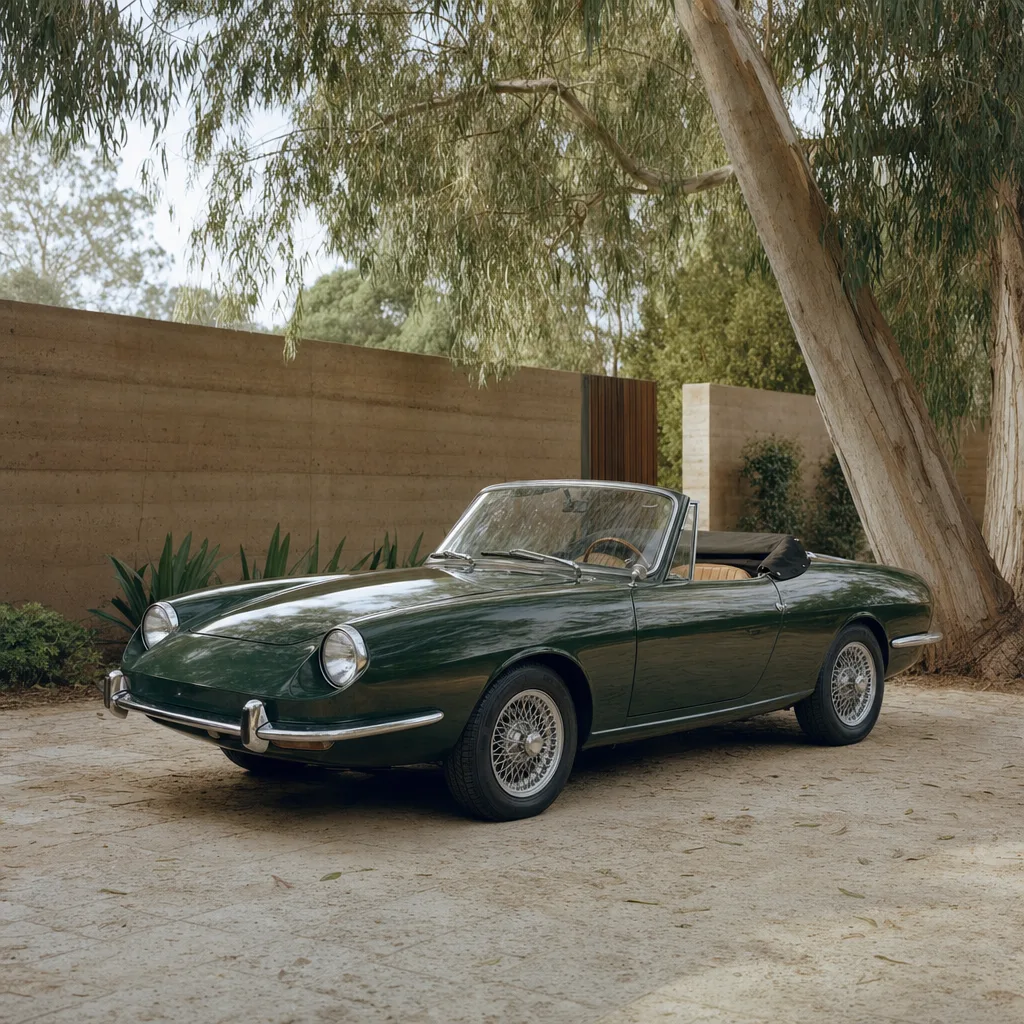
Your cars, at an agreed value.
A prestige or collector car policy covers the car for an agreed value, not a price guide on the day. It usually lets you choose the repairer, covers the car in transit or in someone else’s care, and prices limited use to match. Modifications are covered only if you declare them.
You’ll be asked: the rego or car details, its value (with a valuation for anything unusual), where it’s kept, who drives it and how often, and any modifications. Cars over about $150,000, and classics of any value, go to the prestige specialist on our panel.
The cellar, bottle by bottle.
Cellars are lost to leaks, heat and breakage far more often than theft, and general contents cover rarely handles these well. A wine section covers your collection at replacement cost. Better policies include cooling failure.
You’ll be asked: a cellar list with values (an export from your cellar app is fine), where it’s kept and how it’s cooled. We can help value bottles that can’t be replaced.
Covered anywhere in the world.
Listed jewellery and watches are covered worldwide for loss as well as theft, like a ring lost in the sea or a watch left in a hotel safe. Unlisted pieces fall under your contents, with a per-item limit.
You’ll be asked: a recent valuation for each listed piece, and for the most valuable ones, where they’re kept when you’re not wearing them.
If someone is hurt, or their property is damaged.
Covers you if a guest is injured at your home, or if you or your household are legally responsible for injury or damage elsewhere. It pays legal costs and any amount awarded, up to the policy limit. Limits are set higher for large properties that host guests.
You’ll be asked: about a pool, any staff, and whether any part of the property is rented out.
What each section covers, and its limits and conditions, depend on the policy you choose. Each insurer’s product disclosure statement is linked on its quote and again before you pay. General information only; it doesn’t take your circumstances into account.